
Key Takeaways
- • The article argues that management-adjusted EBITDA in sell-side Confidential Information Memorandums (CIMs) is built to maximize valuation, and that AI chat tools tend to accept add-back explanations at face value rather than testing them against multi-year schedules.
- • A $1.5 million ERP-related add-back recurs under changing labels ($1.2M to $1.5M annually across FY22-FY25); at an 11x multiple, failing to reverse it overstates enterprise value by $16.5 million, according to the author's audit example.
- • Accounts payable were allegedly stretched from a 42-day DPO benchmark to 68 days before sale, creating a $4.1 million Day-1 funding shortfall against the working capital peg if unaudited.
- • A $2.5 million logistics-hub synergy conflicts with same-day delivery SLAs covering 40% of regional revenue, so the claimed savings could trigger customer contract terminations.
- • The author's illustrative audit cuts adjusted EBITDA by $4 million (16.0%) to $21 million, reducing implied enterprise value by $44 million at 11x; this is a vendor-produced example, not an independently verified transaction.
Summary
This piece, published by askOdin and republished under the byline of Chris Churchman's Goldman Sachs AI remarks, contends that management-adjusted EBITDA figures in sell-side CIMs are designed to maximize valuation. The article cites an example in which $18.4 million of operating cash flow is presented as a $25 million premium asset through add-backs such as pro-forma synergies, executive compensation normalization and one-time restructuring costs. It argues that conversational AI tools, which cannot cross-verify narrative claims against multi-year schedules, can produce fluent but unreliable summaries that accept such justifications.
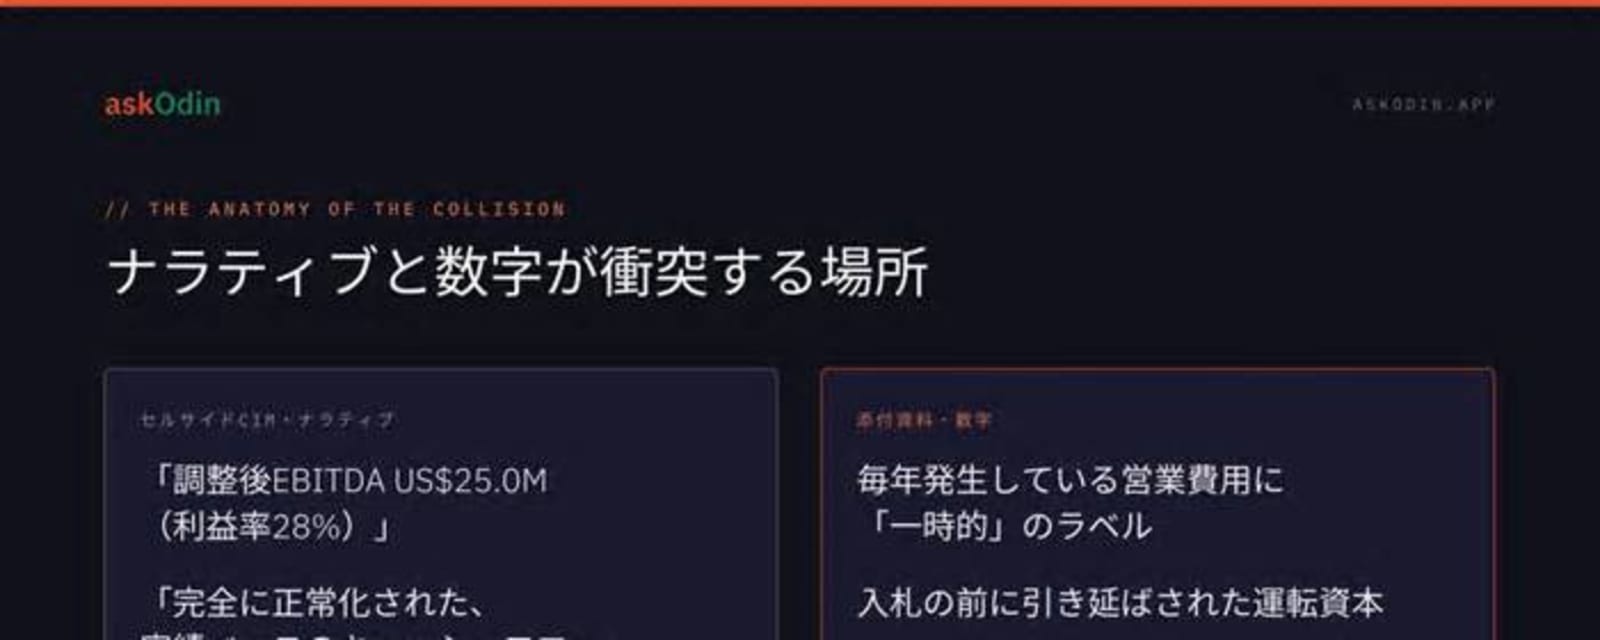
The article identifies three structural fault lines. First, a $1.5 million ERP-related add-back labeled non-recurring recurs every year for four fiscal years under shifting descriptions, from 'system consulting' to 'ERP Optimization.' Second, days payable outstanding reportedly rose from a 42-day 36-month benchmark to 68 days before the sale, which the author says could leave a buyer needing an additional $4.1 million in cash after closing to restore normal vendor payments if the working capital peg is accepted without audit. Third, a claimed $2.5 million in run-rate logistics savings conflicts with same-day delivery service agreements covering roughly 40% of regional revenue.
The author's illustrative recalculation removes $4 million from EBITDA, lowering it to $21 million (-16.0%), and implies a $44 million reduction in enterprise value at an 11x multiple. These figures come from the article's own hypothetical example and are not independently sourced. The piece recommends that investment committees verify add-back persistence, normalized working capital pegs, synergy compatibility with customer contracts, and debt covenant resilience under a 15% EBITDA haircut before signing a letter of intent.
The article identifies three structural fault lines. First, a $1.5 million ERP-related add-back labeled non-recurring recurs every year for four fiscal years under shifting descriptions, from 'system consulting' to 'ERP Optimization.' Second, days payable outstanding reportedly rose from a 42-day 36-month benchmark to 68 days before the sale, which the author says could leave a buyer needing an additional $4.1 million in cash after closing to restore normal vendor payments if the working capital peg is accepted without audit. Third, a claimed $2.5 million in run-rate logistics savings conflicts with same-day delivery service agreements covering roughly 40% of regional revenue.
The author's illustrative recalculation removes $4 million from EBITDA, lowering it to $21 million (-16.0%), and implies a $44 million reduction in enterprise value at an 11x multiple. These figures come from the article's own hypothetical example and are not independently sourced. The piece recommends that investment committees verify add-back persistence, normalized working capital pegs, synergy compatibility with customer contracts, and debt covenant resilience under a 15% EBITDA haircut before signing a letter of intent.
Go deeper than the headline
Research every firm in this story, track the ones that matter and get the daily briefing — free for 7 days.